BANGKOK — In a landmark development at the International Monetary Fund (IMF) and World Bank 2026 Annual Meetings, global financial leaders have introduced a comprehensive new framework designed to fortify the international financial architecture against increasingly sophisticated cyber-enabled fraud.
Unveiled on Wednesday, October 14, 2026, at the Queen Sirikit National Convention Center (QSNCC) in Bangkok, Thailand, the initiative—officially titled the Bangkok Blueprint for Fraud-Resilient Financial Services—arrives as governments and regulators grapple with a digital crime wave that is draining trillions of dollars from the global economy and eroding public trust in digital finance.
The release of the framework coincides with a broader session of market volatility. Domestic Indian indices closed lower on the day of the announcement, with the benchmark SENSEX sliding 312.53 points to settle at 72,721.25, and the NIFTY dropping 110.05 points to 22,611.90. Meanwhile, commodities experienced mixed movements: crude oil climbed ₹35.00 to ₹8,988.00, whereas precious metals saw notable corrections, with gold declining by ₹578.00 to ₹147,872.00 and silver plunging ₹1,857.00 to close at ₹217,360.00.
Despite the day’s financial market fluctuations, the overarching sentiment in Bangkok remained intensely focused on the systemic risks posed by borderless cyber-scams and the urgent imperative for coordinated regulatory defense.
Main Facts
The Bangkok Blueprint for Fraud-Resilient Financial Services represents a collaborative effort by international financial institutions to address the escalating threat of cyber-enabled fraud, which has grown exponentially alongside the global adoption of digital banking and fintech solutions.
- Nature of the Blueprint: The framework is structured as a strategic advisory toolkit aimed at assisting policymakers, regulatory authorities, financial institutions, and other key stakeholders. However, organizers clarified that it does not constitute formal, binding IMF-World Bank policy guidance.
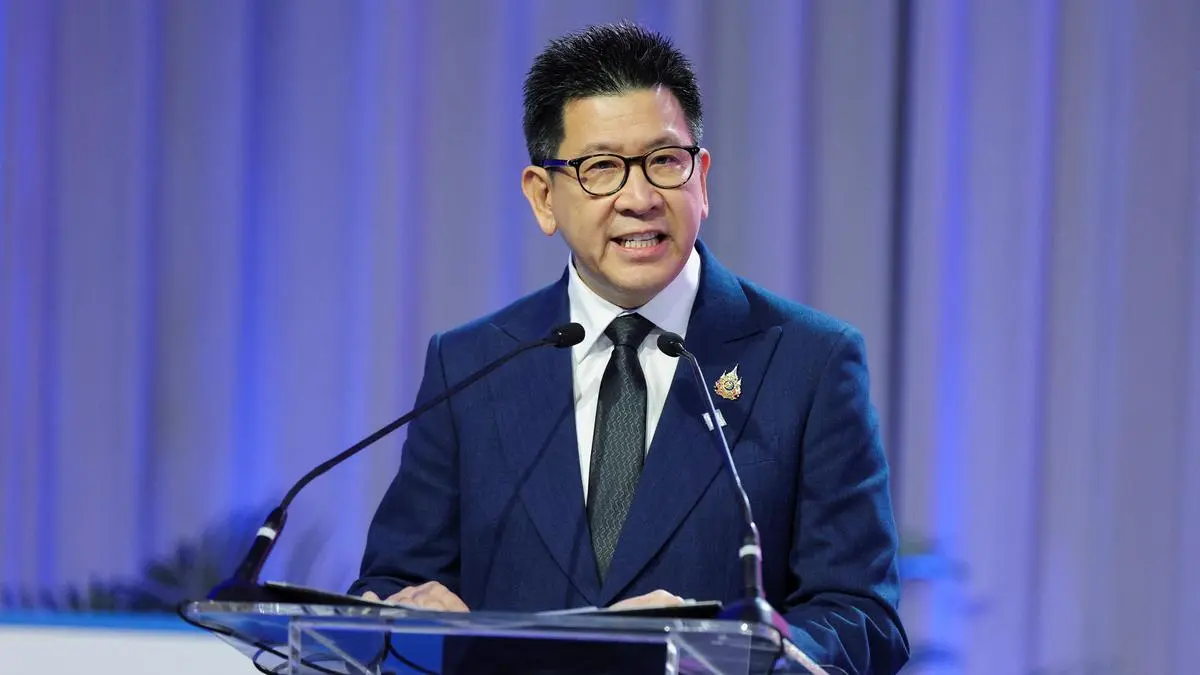
- The Global Economic Toll: Speaking at the launch event, Thailand’s Deputy Prime Minister and Finance Minister Ekniti Nitithanprapas highlighted the staggering macro-economic impact of digital scams. "Digital fraud and scams have become a global problem," Nitithanprapas stated. "It has cost the world economy around $1 trillion annually, or 3% of global GDP."
- Regional Epicenter: According to data from the United Nations Office on Drugs and Crime (UNODC), the Asia-Pacific region has emerged as a primary target and operational base for transnational crime syndicates. In 2025 alone, scam networks defrauded residents in the region of at least $88 billion.
- Threat to Financial Inclusion: IMF Managing Director Kristalina Georgieva warned that the unchecked proliferation of cyber-fraud threatens to reverse hard-won gains in financial inclusion. Digital finance has historically served as a vital bridge, bringing unbanked populations into the formal economic ecosystem; however, rising scams threaten to alienate vulnerable users who fear digital exploitation.
Chronology: The Escalation of the Global Scam Crisis
To understand the urgency behind the Bangkok Blueprint, financial historians and security experts point to a clear trajectory of escalating cyber criminality over recent years:
- The Post-Pandemic Digital Boom (2021–2022): As global populations shifted rapidly toward digital payments, mobile wallets, and online banking during and immediately after the COVID-19 pandemic, bad actors seized the opportunity. Cyber-fraud transitioned from isolated phishing attempts to industrialized, transnational enterprises.
- The Rise of Industrialized Scams in Southeast Asia (2023–2024): Transnational criminal syndicates established sprawling compounds across parts of Southeast Asia, utilizing human trafficking and forced labor to run industrial-scale romance scams, cryptocurrency investment frauds ("pig butchering"), and call-center operations. By the end of 2024, data shared by the Bank of Thailand indicated that Asia accounted for a staggering 67% of total global fraud losses.
- The $88 Billion Threshold (2025): Despite mounting national law enforcement crackdowns and regional task forces, organized crime groups rapidly evolved their tactics—incorporating generative artificial intelligence, deepfakes, and decentralized cryptocurrency laundering networks—to stay several steps ahead of authorities. UNODC figures confirmed that victims in the Asia-Pacific region lost a minimum of $88 billion in 2025.
- The Bangkok Consensus (October 2026): Recognizing that localized law enforcement and fragmented banking protocols are insufficient against borderless syndicates, the IMF and World Bank leveraged their 2026 Annual Meetings in Bangkok to formulate a unified, cross-border defense strategy, culminating in the release of the Bangkok Blueprint.
Supporting Data and Regional Insights
The scale of the cyber-fraud epidemic is underscored by empirical data compiled by international bodies, central banks, and anti-fraud agencies.
Global and Regional Metrics
- $1 Trillion: The estimated annual cost of digital fraud to the global economy, equivalent to approximately 3% of global Gross Domestic Product (GDP).
- 67%: The proportion of global fraud losses concentrated in Asia in 2024, highlighting the region’s acute vulnerability and immediate exposure to organized cyber syndicates.
- $88 Billion: The minimum amount stolen from residents in the Asia-Pacific region in 2025 alone, according to UNODC reports.
Bank of Thailand Governor Vitai Ratanakorn emphasized that while Asia has borne the heaviest losses, it has also accumulated critical operational experience in combating these threats. "The region has accumulated valuable experience combating this threat, offering up practical lessons that countries can adapt to their own contexts," Ratanakorn noted during the meetings. He stressed that defensive measures implemented by Southeast Asian central banks—such as stricter biometric verification for mobile banking applications, mule-account tracking, and real-time transaction monitoring—could serve as a blueprint for other emerging and developed markets.
Official Responses and Perspectives
The launch of the Bangkok Blueprint drew high-profile endorsements and critical commentary from global financial architects and government leaders attending the Bangkok meetings.
-
Ekniti Nitithanprapas, Thailand’s Deputy Prime Minister and Finance Minister:
"Digital fraud and scams have become a global problem. It has cost the world economy around $1 trillion annually, or 3% of GDP. We must unite across borders to establish resilience, just as we do for traditional financial shocks."

-
Kristalina Georgieva, Managing Director, International Monetary Fund (IMF):
"The expansion of cyber fraud is threatening to reverse the gains made by digital finance. Digital tools allowed millions of people who otherwise have no access to the financial system to finally access it. If security and trust are undermined, we risk pushing these vulnerable populations back into the informal, cash-based economy."
-
Vitai Ratanakorn, Governor, Bank of Thailand:
"Asia accounted for 67% of global fraud losses in 2024. The region has accumulated valuable experience combating this threat, offering up practical lessons that countries can adapt to their own financial landscapes."
Implications for Financial Institutions and Policymakers
The introduction of the Bangkok Blueprint carries profound implications for stakeholders across the global financial ecosystem. While the document is advisory rather than mandatory, it sets a new benchmark for what regulators and institutions will be expected to implement in the coming years.
1. Regulatory Compliance and Cross-Border Collaboration
Financial regulators worldwide will likely face increased pressure to harmonize their anti-fraud regulations. Because cyber-criminals exploit regulatory arbitrage between jurisdictions—moving illicit funds across borders through shell companies and crypto-mixers—the Blueprint urges central banks and financial intelligence units (FIUs) to establish real-time intelligence-sharing mechanisms.
2. Technological Upgrades for Commercial Banks
Commercial banks and fintech firms will be compelled to invest heavily in advanced fraud-detection technologies. Traditional rule-based transaction monitoring systems are no longer adequate against AI-generated fraud vectors. Institutions will need to adopt behavioral biometrics, machine learning algorithms capable of detecting anomalous account activity instantly, and robust Know-Your-Customer (KYC) protocols.
3. Protecting Financial Inclusion
As Managing Director Georgieva pointed out, the ultimate casualty of unmitigated digital fraud is public trust. If retail banking customers—particularly newly onboarded, digitally literate populations in emerging markets—feel that their life savings can be wiped out via sophisticated phishing or scam operations without recourse, they may abandon digital platforms altogether. Restoring and maintaining trust is therefore identified as an economic imperative, not merely a compliance check.
4. Market and Economic Fallout
As demonstrated by ongoing market volatility—reflected in shifting indices like the SENSEX and NIFTY, alongside fluctuations in crude oil and precious metals—investors are increasingly factoring systemic technological and operational risks into asset valuations. Financial institutions that fail to secure their digital infrastructure face not only direct regulatory penalties and remediation costs, but also severe reputational damage that can depress institutional equity values.
Looking Ahead
As the IMF and World Bank 2026 Annual Meetings proceed in Bangkok, the Bangkok Blueprint for Fraud-Resilient Financial Services serves as a clarion call to the international community. Whether policymakers and financial institutions can effectively operationalize its recommendations to outpace agile, transnational cyber syndicates remains the defining test for the future stability of the global digital economy.