










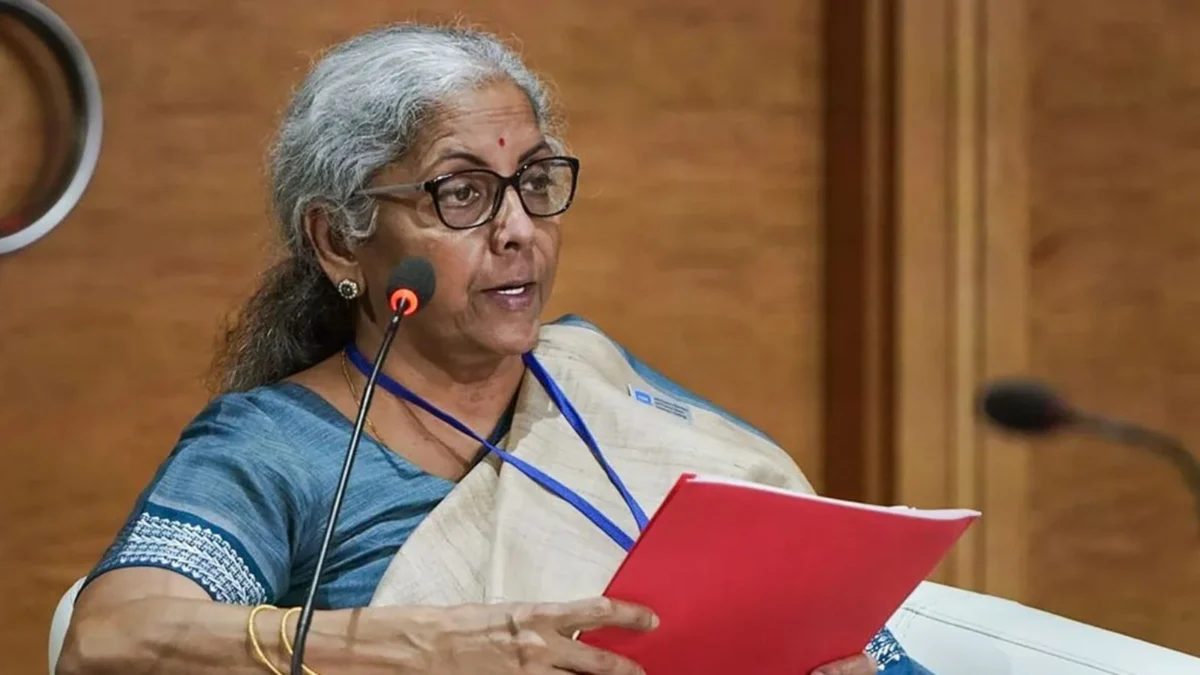
NEW DELHI — Indian benchmark stock indices experienced a sharp intraday upswing on Tuesday, propelled by remarks from Finance Minister Nirmala Sitharaman at the prestigious Bloomberg New Economy Forum. Addressing a global audience of economists, policymakers, and investors, Sitharaman described ongoing discussions surrounding the long-term capital gains (LTCG) tax as “healthy” and signaled her willingness to engage with stakeholders on the matter.
Her comments, delivered during active market hours, served as a strong psychological boost for investors. The BSE Sensex extended its morning gains to close the session 1.5% higher, while the broader NSE Nifty 50 advanced by 1.6%.
Beyond taxation, Sitharaman addressed macroeconomic stability, foreign capital flows, and the Reserve Bank of India’s (RBI) persistent interventions in the foreign exchange market to curb excessive volatility in the rupee.
1. Main Facts
The core developments from the Finance Minister’s address and the contemporary macroeconomic landscape include:
- Openness to Tax Dialogue: Sitharaman acknowledged that the discourse on the long-term capital gains (LTCG) tax and the Securities Transaction Tax (STT) is robust. While stopping short of committing to tax cuts ahead of the upcoming Union Budget, she welcomed continuous stakeholder engagement.
- Market Reaction: Domestic equities surged following her statements. The Sensex and Nifty closed up 1.5% and 1.6%, respectively, buoyed by hopes of future fiscal rationalization.
- RBI’s Currency Stance: The Finance Minister clarified that while the RBI will actively step in to curb destabilizing volatility in the rupee, it has no intention of artificially “fixing” an exchange rate, allowing the currency to discover its natural equilibrium.
- Foreign Portfolio Outflows: Foreign Portfolio Investors (FPIs) have pulled out substantial capital, net-selling $16.6 billion in Indian equities and debt during the 2025–26 fiscal year, with an additional $14 billion pulled out in the current fiscal cycle.
- Rupee Stabilization: Supported by recent aggressive interventions and liquidity-tightening measures by the RBI over the weekend, the rupee recovered, gaining 1% on Monday and 0.5% on Tuesday to close at 95.28 against the US dollar.
2. Chronology of Events
To understand the trajectory of policy discussions and market movements leading up to Tuesday’s rally, a chronological examination is essential:
- May 2025: Amid intensifying geopolitical tensions in West Asia and a strengthening US dollar, foreign capital flight accelerates, pushing the Indian rupee dangerously close to the 97-per-dollar psychological threshold.
- June 5, 2025: In a decisive move to attract overseas capital and relieve pressure on the currency, the central government scraps withholding taxes, as well as long-term and short-term capital gains taxes, specifically on foreign investments in government bonds. Previously, these investments attracted a 12.5% LTCG tax, a 30% short-term capital gains tax, and a ~20% withholding tax.
- October 9, 2025: State Bank of India’s (SBI) Group Chief Economic Adviser, Soumya Kanti Ghosh, publishes a critical economic report. Ghosh calls for a strategic review of the capital gains and tax structure to enhance "patient capital" inflows into debt and equities, arguing that India faces a fierce global fight for capital.
- October 12, 2025: The Ministry of Finance officially commences its exhaustive pre-budget consultations for the upcoming 2027–28 Union Budget, which is traditionally presented in Parliament on February 1.
- Early October 2025: The rupee flirts with its historic low of 96.96 per dollar. In response, the RBI announces stringent measures over the weekend to dampen speculative forex market activity and increase the cost of hedging forex exposures.
- Tuesday, October XX, 2025: Finance Minister Sitharaman speaks at the Bloomberg New Economy Forum during active trading hours, validating the ongoing public debate over capital gains taxes and reaffirming the government’s comfort with the RBI’s currency management strategy. Markets respond instantly with a 1.5% to 1.6% rally.
3. Supporting Data and Financial Metrics
The intricate dynamics connecting fiscal policy, taxation, and currency valuations are underscored by several key figures:
- Current Capital Gains Taxation: India levies a standard 12.5% tax on long-term capital gains, triggered when financial or physical assets are sold after being held for more than one year.
- Foreign Institutional Outflows: FPI divestment has been severe. Net outflows touched $16.6 billion across 2025–26, and the trend has persisted into the current fiscal year, with cumulative net sales already reaching $14 billion.
- Exchange Rate Movements: Prior to the RBI’s weekend intervention, the rupee neared an all-time low of 96.96 per dollar. Following regulatory tightening, the currency rebounded strongly over two consecutive sessions, appreciating by 1% on Monday and 0.5% on Tuesday to settle at 95.28 per dollar.
- Budgetary Timeline: The comprehensive planning cycle for the Union Budget spans nearly four months, starting with preliminary consultations in mid-October and culminating on Budget Day, slated for February 1.
4. Official Responses and Policy Stance
When pressed by foreign investors regarding expectations of capital gains tax reductions to catalyze investment, Sitharaman adopted a pragmatic and measured tone. Noting that the preparatory cycle for the 2027–28 Union Budget is already underway, she emphasized the need for caution: "Considering that work on the Union Budget has begun, it may not be the best time for me to say what I will or what I will not consider. So, I’ll tread cautiously on that."
Sitharaman reflected on past structural tax adjustments, particularly the efforts made two years prior to harmonize asset classes. "Two years ago, we had brought all asset classes similarly and people thought I’m increasing the tax. I wasn’t increasing the tax; I was bringing all of them to be at par with one another so that an investor is not speculating as to which one gives them greater leverage," she explained. She added that while opinions vary, the ongoing discourse remains a constructive indicator of market vitality.
Regarding exchange rate management, the Finance Minister offered unequivocal backing to the central bank. She noted that the RBI’s aggressive interventions are designed to curb disorderly market movements rather than dictate an artificial value for the currency. "These efforts from RBI, I understand, will continue, not to fix the rupee. We would appreciate if the rupee finds its own level," Sitharaman stated.
She further attributed the persistent depreciation of the rupee over the preceding eighteen months to external macroeconomic headwinds rather than domestic policy failures, reassuring investors that the government’s commitment to fiscal discipline remains unshakeable. "Our fiscal discipline is not going to be a matter which should worry investors. But as regards the rupee and the way it is reacting to the ups and downs with the dollar, yes, that’s where the challenge is and we will be attending to that."
5. Broader Market Implications
The intersection of taxation policy, institutional capital flows, and currency stability carries profound implications for India’s economic trajectory:
The Global Fight for Capital
As noted by economic analysts like SBI’s Soumya Kanti Ghosh, emerging economies are locked in an increasingly aggressive competition for cross-border investments. With global liquidity tightening and non-artificial intelligence (AI) traditional sectors facing headwinds, India must continuously evaluate its tax competitiveness. The market interprets Sitharaman’s willingness to listen as a potential opening for policy recalibration in the upcoming budget.
Balancing FPI Sentiment and Domestic Savings
While domestic institutional investors (DIIs) and retail investors via systematic investment plans (SIPs) have provided a strong structural cushion to Indian capital markets, the persistent exit of FPIs—totaling over $30 billion across recent quarters—places a heavy burden on domestic liquidity. Addressing foreign investor grievances regarding LTCG and STT could trigger a renewed wave of overseas inflows, although policymakers must balance this against revenue collection targets and tax parity across asset classes.
Macroeconomic Resilience vs. Currency Pressures
The RBI’s recent actions demonstrate the central bank’s resolve to prevent speculative attacks on the rupee. However, sustainable currency stabilization ultimately depends on narrowing current account deficits, boosting export competitiveness, and encouraging steady inward remittances and foreign direct investment (FDI). Sitharaman’s assurance that fiscal prudence will not be compromised provides a solid anchor for investor confidence, even as external currency pressures demand vigilant management.
In summary, the Finance Minister’s address has successfully bridged immediate market anxieties with long-term policy predictability. By validating public debate on taxation without making premature commitments, and by backing the RBI’s pragmatic approach to exchange rate volatility, the government has reinforced its reputation for responsive and stable economic management.



