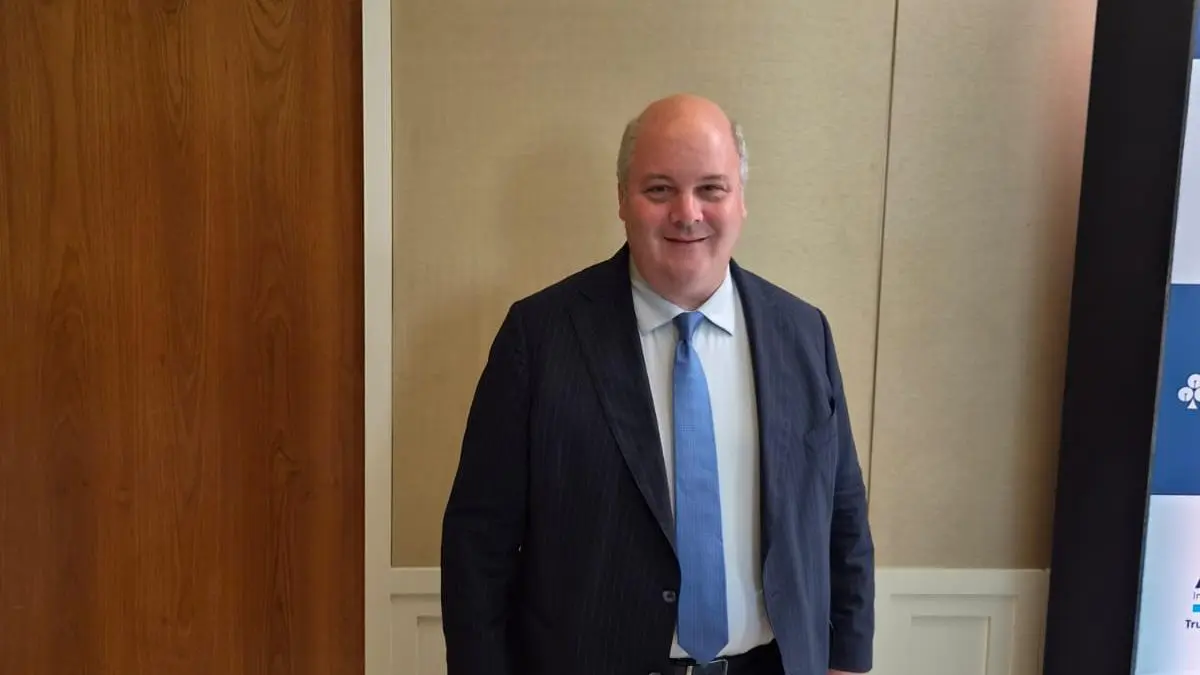
PARIS / NEW DELHI — As global capital overwhelmingly crowds into the US technology sector and artificial intelligence (AI) winners, a major counter-narrative is quietly taking shape in institutional boardrooms. Vincent Mortier, Deputy CEO and Group Chief Investment Officer of Amundi—Europe’s largest asset manager overseeing a staggering €2.6 trillion—is bucking the consensus. While many international investors have temporarily sidelined emerging markets in favor of Silicon Valley darlings, Mortier and his team maintain an aggressive, overweight stance on India.
In a wide-ranging strategic assessment, Amundi’s investment chief addressed the structural underrepresentation of emerging economies in global indices, the impending hurdles facing the AI monetization cycle, a shifting commodity supercycle, and why India’s macroeconomic fundamentals make it one of the most compelling destinations for patient capital.
Main Facts: The Core Investment Thesis on India
Amundi’s bullish posture on India is built on a foundation of macroeconomic resilience, favorable demographic trends, and a belief that global capital has momentarily mispriced the South Asian powerhouse due to short-term cyclical headwinds.
- The Weight of Capital: Managing €2.6 trillion gives Amundi a panoramic view of global liquidity flows. Mortier confirms that the firm is significantly overweight on India, Latin America, and Eastern Europe relative to benchmark indices.
- The AI Blindspot: Over the past two years, India has occasionally fallen "out of fashion" among global institutional portfolios. Mortier attributes this to two primary misconceptions: that India lacks exposure to the structural AI boom, and that the country is excessively vulnerable to energy supply shocks, protectionist tariffs, and geopolitical volatility.
- The Currency Resilience: Addressing historical concerns regarding the depreciation of the Indian rupee (INR), Mortier argues that the medium-term outlook for the currency is protected. Unlike the United States, Europe, and the United Kingdom—all of which face severe fiscal deficits and structural public debt refinancing pressures—India’s macro trajectory provides a natural buffer for the rupee.
- Benchmark Disconnect: Mortier asserts that standard global equity benchmarks fundamentally understate India’s true economic importance. Based on market capitalization and GDP growth, India deserves a significantly higher allocation in global indices than it currently holds.
Chronology and Context: How India Slipped Out of Fashion
To understand India’s current positioning in global portfolios, it is necessary to examine the macro shifts of the past 24 months.
Phase 1: The Post-Pandemic Rebound and Initial Reforms
Following the global disruptions of the COVID-19 pandemic, India emerged as one of the fastest-growing major economies. Structural economic reforms, aggressive digitalization, and formalization of the economy drew initial waves of foreign institutional investment (FII). During this window, international investors frequently scrutinized India’s regulatory complexity and taxation frameworks. However, these anxieties have steadily dissipated. According to Amundi, client concerns regarding India’s tax regime—once a recurring friction point—have largely evaporated, replaced by discussions centered purely on growth prospects and fundamental market opportunities.
Phase 2: The Global AI Gold Rush
Beginning in late 2022 and accelerating through 2023 and 2024, global capital experienced a historic gravitational pull toward generative AI. Wall Street and international tech ecosystems dominated institutional inflows. Because India’s equity market is anchored heavily in domestic consumption, financial services, industrials, and IT services rather than speculative hyper-growth AI hardware monopolies, it experienced relative outflows as portfolio managers reallocated dry powder toward US mega-cap tech stocks.
Phase 3: The Current Inflection Point
Today, Amundi views the market as standing at a critical crossroads. As questions mount regarding the actual return on investment (ROI) for multi-billion-dollar AI infrastructure projects, institutional investors are beginning to re-evaluate over-concentrated portfolios. This realization is breathing new life into neglected geographies, positioning India as a prime beneficiary of a potential portfolio rotation back toward fundamental value, reasonable valuations, and sustainable earnings growth.
Supporting Data and Market Dynamics
Amundi’s strategic asset allocation is backed by a meticulous evaluation of global monetary trends, commodity cycles, and valuation metrics across regions.
1. The Monetization Wall Facing Artificial Intelligence
Mortier casts a cautious eye on the relentless rush of capital into data centers, memory chips, and frontier AI models like OpenAI and Anthropic. The central issue, he warns, is the monetization gap.
"We are seeing more and more models emerge, including inexpensive open-source alternatives. For the vast majority of use cases, you do not need frontier models. You need relatively simple models," Mortier explains.
As open-source solutions proliferate, the price of tokens is expected to decline annually. This structural deflationary pressure on AI services will create a pricing-related drag on earnings. Consequently, Amundi believes that current market consensus regarding aggregate tech earnings growth is overly optimistic, setting the stage for a reckoning that could deflate tech valuations and force a broader search for yield.
2. The Commodity Supercycle and Traditional Sectors
Beyond equities, Amundi is aggressively positioning itself in asset classes that hedge against inflation and structural supply constraints. The firm likes dividend-paying assets, basic resources, and gold.
- The Copper Thesis: Mortier notes that the world is merely at the beginning of a multi-year commodity supercycle, with copper leading the charge due to its critical role in electrification, grid modernization, and renewable energy infrastructure.
- Renewable Energy and Value Plays: Capital-intensive sectors that suffered during the high-interest-rate environment—such as utilities and pharmaceuticals—have become increasingly attractive as valuations normalized. Simultaneously, renewable energy players have transitioned from speculative ventures into genuinely profitable commercial enterprises.
3. Personal Conviction: Putting Skin in the Game
Demonstrating institutional alignment with his personal convictions, Mortier revealed that he recently re-established his personal exposure to India. Having sold his direct India holdings roughly six months prior, he bought back into the market two weeks ago via a Nifty-linked Exchange Traded Fund (ETF). India currently comprises approximately 3% of his overall personal portfolio and roughly 10% of his equity allocation.
Official Responses and Institutional Perspectives
The debate over India’s weight in global indices and its appeal as an investment destination touches on broader governance issues within global finance.
The Index Provider Dilemma
For decades, global benchmark providers (such as MSCI and FTSE Russell) have utilized methodologies based on free-float market capitalization, foreign ownership limits, and liquidity metrics. While these frameworks serve a purpose, asset managers like Amundi argue that they create structural distortions.
- The Weighting Gap: India’s GDP now ranks among the top five globally, and its equity market capitalization frequently competes for the fourth or fifth largest spot in the world. Yet, its weight in benchmark emerging market indices fails to mirror this reality.
- The FII Perspective: While index providers move cautiously, active managers with large-scale mandates are no longer waiting for mechanical benchmark adjustments. By going "overweight" independently of index constraints, firms like Amundi are proactively capturing growth that benchmarks structurally overlook.
The European Parallel: Navigating Structural Change
Drawing a parallel to his home market in Europe, Mortier notes that international investors often view Europe and India through a similar lens—neither is perceived as an AI pure-play. However, Europe is undergoing a monumental strategic awakening. Propelled by Germany and other continental leaders, Europe is heavily investing in defense, energy independence, and infrastructure to secure its strategic autonomy.
While Europe faces the ongoing challenge of financing these investments through targeted public spending cuts and fiscal reallocations, the underlying drive toward higher self-reliance and growth mirrors the domestic reform momentum seen in India.
Implications for Global Investors
Amundi’s strategic outlook offers clear takeaways for institutional and retail investors navigating the remainder of the decade:
- Diversification is Back: The era of blindly concentrating portfolios in a handful of US mega-cap AI stocks may be reaching a point of diminishing returns. Smart money is actively rotating toward diversified, high-growth emerging markets.
- Valuation Discipline Matters: With AI token prices declining and earnings expectations facing headwinds, valuation discipline will separate sustainable portfolios from those exposed to a tech correction. India’s robust domestic growth offers a defensive yet high-beta buffer against US tech volatility.
- Currency Realities are Shifting: As Western economies wrestle with ballooning public debt and fiscal deficits, emerging market currencies like the Indian rupee are expected to find structural support against traditional safe-haven pressures in the medium term.
- The Rise of Real Assets: Pairing emerging market equities with commodities, copper, and cash-flow-positive traditional sectors (like pharmaceuticals, utilities, and renewables) forms the bedrock of Amundi’s blueprint for navigating a complex macroeconomic landscape.
As global markets digest the limits of the AI trade, the institutional weight behind India is unlikely to recede. For asset giants managing trillions, the country is no longer an alternative play—it is an indispensable engine of global economic growth.