By Industry Correspondent
October 25, 2026
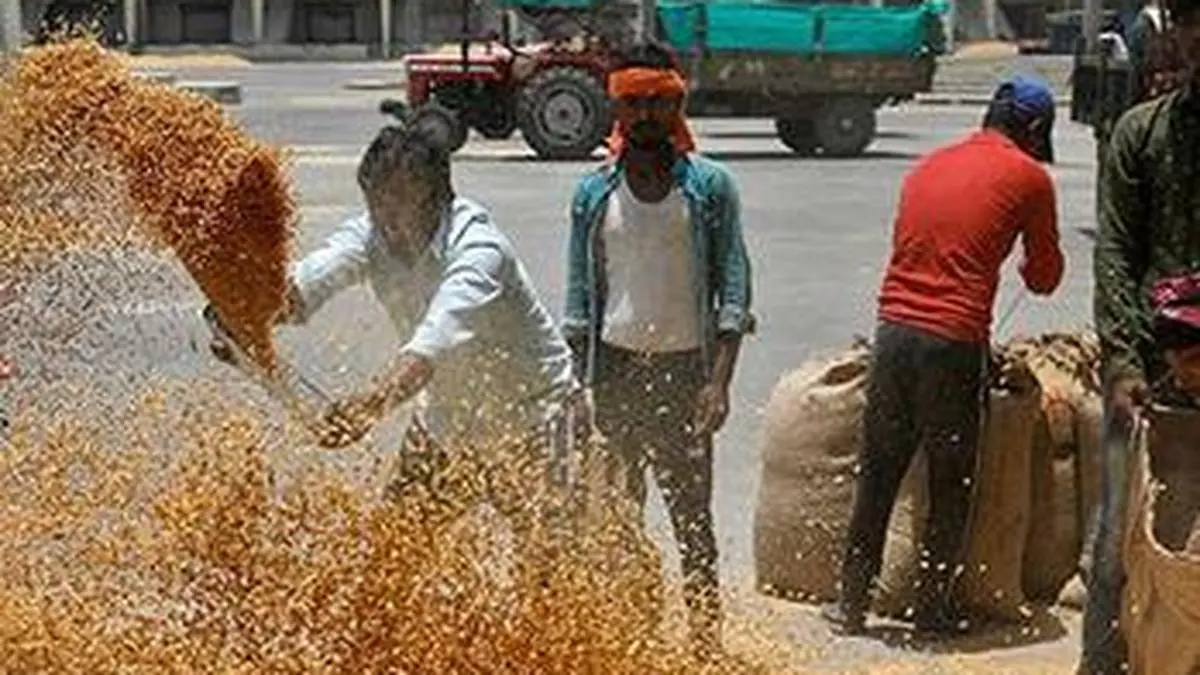
The Indian wheat market is currently navigating a period of paradoxical tension. Despite government reports of record-breaking production and comfortable buffer stocks, flour millers across the nation are reporting a severe supply crunch in the open market. This disparity has culminated in a direct plea from the milling industry to the Union government, urging a significant and progressive increase in the quantity of wheat released through weekly auctions conducted by the Food Corporation of India (FCI).
As of late October 2026, the government has opted to tighten the tap, reducing the total wheat allocation for the upcoming auction on October 28 by 5,000 tonnes, bringing the total to 1.01 lakh tonnes (lt). This decision comes at a time when processors are aggressively bidding for grain, often paying prices exceeding ₹3,100 per quintal—well above the national average wholesale price of ₹2,910 per quintal.
The Core Conflict: Supply Stagnation vs. Rising Demand
The tension between the government’s allocation strategy and the ground-level reality faced by millers has reached a breaking point. Industry leaders argue that the "open market" availability of wheat is far more constrained than official estimates might suggest.
"It seems there is not as much wheat in the market as was earlier thought," says Dharmendra Jain, President of the Roller Flour Millers’ Federation of India. According to Jain, the scarcity is driving millers to rely almost exclusively on FCI auctions to keep their operations running. When the government restricts these auctions, the immediate result is an inflationary spike in wholesale prices, which eventually trickles down to the end consumer in the form of higher flour (atta) prices.
The Federation has formally communicated to the government that the current auction volumes are insufficient to satisfy the milling industry’s operational requirements. They are advocating for a more flexible, demand-driven approach that increases supply in regions where consumption and processing capacity are highest.
Chronology of the Recent Auction Trends
To understand the friction, one must look at the recent shifts in FCI auction data:

- Mid-October (October 16): The baseline for current calculations, where allocations were distributed across various states based on demand projections.
- October 21 Auction: A high-activity round where several states witnessed near-total offtake, signaling strong demand.
- October 25 (Current Outlook): The government announces a reduction in the aggregate allocation for the October 28 auction by 5,000 tonnes compared to the previous week.
- Regional Variance: While the national total was lowered, the government engaged in a "rebalancing" act. States like Maharashtra, Punjab, and West Bengal saw an increase in their allocations, while states like Assam, Karnataka, and Telangana faced sharp cuts despite having demonstrated 100% offtake capacity in the previous round.
Regional Disparities: A Geographic Snapshot
The government’s decision to reduce quotas in specific high-demand states has left regional millers perplexed. The data reveals a clear disconnect between local demand and central allocation:
- Assam: In the October 21 round, millers bought 7,940 tonnes out of the 8,000 tonnes offered. Despite this near-total utilization, the allocation for the upcoming auction has been slashed to 5,000 tonnes.
- Telangana: Millers purchased 3,460 out of 3,500 tonnes in the last round. The new allocation is just 1,000 tonnes.
- Karnataka: With a successful bid of 5,430 out of 6,000 tonnes previously, the state now faces a reduction to 5,000 tonnes.
While officials have justified the reduction in states like Odisha—where demand was sluggish, with only 3,050 tonnes sold out of 6,000—millers argue that the same logic cannot be applied to states where the grain is being bought as soon as it hits the auction block.
Conversely, Punjab has seen its allocation climb to 25,000 tonnes, up from 23,000 tonnes. The intensity of the market in Punjab is evident: 204 processors competed for wheat, with 8,970 tonnes sold at a premium price of ₹3,000 per quintal or higher.
Structural Bottlenecks: The Case for Reform
Beyond the volume of the auctions, industry experts are calling for a structural overhaul of how these auctions are conducted. Naresh Ghai, President of the Roller Flour Mills Association of Punjab, has been vocal about the "one-size-fits-all" approach to depot allocations.
"The offered quantity in a single depot should be decided based on the concentration of mills in the surrounding areas rather than putting a maximum cap of 500 tonnes per week," Ghai asserts. He points to Ludhiana as a prime example; the city houses 18 mills that account for 20% of Punjab’s total milling capacity, yet it receives the same allocation as depots in areas with significantly lower processing needs.
Ghai suggests that the weekly allocation for Punjab should be increased to 40,000 tonnes to account for the current state of "zero arrival" of fresh wheat in the mandis. Without a change in policy, he predicts that wheat prices will continue to remain high, showing no signs of easing in the near term.
Supporting Data: The Production-Stock Paradox
The current situation is particularly confusing given the macro-economic data provided by the government. As of September 1, 2026, the FCI reported a wheat stock of 479.92 lakh tonnes—the highest on that date in the last five years.

Furthermore, the production numbers tell a story of abundance:
- 2025-26 Crop Year: Record production of 120.66 million tonnes (mt), up from 117.95 mt the previous year.
- Procurement: The government successfully procured 357.57 mt in the 2026-27 season, significantly higher than the 299.75 mt procured in the previous marketing season.
If stocks are at a five-year high and production has hit record levels, why is the market starved? Analysts suggest several possibilities:
- Hoarding Concerns: There is speculation that private players and intermediaries are holding back stocks in anticipation of further price hikes.
- Consumption Patterns: Increased demand from the processed food sector and the organized retail sector may be outstripping the government’s current supply release velocity.
- Logistics and Distribution: While the grain exists in warehouses, the velocity of its movement into the hands of the millers may be hindered by bureaucratic bottlenecks or misaligned allocation logic.
Implications for the Future
The implications of this standoff are multifaceted. For the milling industry, the current environment is one of extreme volatility. Small and medium-sized millers, who lack the capital to compete in aggressive bidding wars, are at the highest risk of being priced out of the market.
For the government, the challenge is to balance the need to curb food inflation with the requirement to maintain sufficient strategic reserves. If they continue to hold back supplies, they risk a sustained increase in the price of essential commodities like bread and flour, which can lead to social and political pressure.
As the industry looks toward the next set of auctions, the consensus among stakeholders is clear: the government must pivot from a restrictive supply posture to a more facilitative one. Unless the FCI increases the weekly auction quotas to reflect actual market demand, the gap between the "official" price of wheat and the "real-world" cost for processors will likely continue to widen, keeping inflation in the food basket elevated well into the final quarter of the year.
The government is now under significant pressure to provide a transparent rationale for its allocation cuts and to address the structural inequalities in its depot-based distribution system. Whether they choose to heed the advice of the Roller Flour Millers’ Federation remains the pivotal question for the weeks ahead.