

By Sumit Chakraborty
Enriched & Expanded Coverage
Main Facts
In a testament to the surging power of African mobile financial services, Airtel Money has officially commenced trading its shares on the London Stock Exchange (LSE), boasting a staggering valuation of approximately $7 billion. Behind this headline-grabbing market entry, however, lies an astonishing corporate paradox: a fintech giant operating at continental scale with a skeletal direct headcount.
Consider the operational footprint of the firm:
- Uganda: 57 employees.
- Zambia: 31 employees.
- Kenya: 13 employees.
Across its entire corporate footprint spanning 13 African countries, Airtel Money maintains just over 300 formal employees on its payroll. Yet, during the 2026 fiscal year (FY26), the company generated a phenomenal $1.35 billion in revenue. This translates to more than $4 million in revenue per head—an efficiency ratio that dwarfs traditional banking institutions and even outpaces many of Silicon Valley’s hyper-scaled software-as-a-service (SaaS) firms.
However, this microscopic internal workforce is entirely subsidized by a massive decentralized army. Airtel Money relies on a network of over 2.3 million external agents—predominantly local, small-shop owners scattered across urban centers and rural outposts throughout sub-Saharan Africa—who execute the heavy lifting of customer acquisition, cash-in, and cash-out transactions.
Chronology of Evolution: From Telecom Expansion to Fintech Spin-Off
To understand how Airtel Money reached its current valuation, one must trace the convergence of telecommunications infrastructure and financial exclusion across emerging markets over the past two decades.
- The Early 2000s (The Mobile Penetration Boom): As mobile network operators (MNOs) aggressively expanded infrastructure across Africa, mobile phone adoption skyrocketed. However, formal banking infrastructure remained sparse, leaving millions unbanked.
- The Rise of Telco-Led Wallets: Recognizing that airtime functioned as a surrogate currency, operators began building proprietary wallets linked directly to SIM cards. Airtel Africa integrated its mobile money services deeply into its overarching telecom subscriber base, ensuring that every wallet holder was first an Airtel mobile customer.
- Mid-2010s (Scaling the Agent Network): Rather than building physical bank branches, Airtel Money weaponized the informal retail economy. By turning neighborhood grocery stalls, kiosks, and airtime vendors into "agents," the company built a ubiquitous cash-in/cash-out (CICO) distribution web without incurring massive CapEx liabilities.
- FY25–FY26 (Institutional Maturation): Airtel Money cemented its financial independence. The parent telecom company, Airtel Africa, leaned heavily on the fintech arm for internal B2B services—such as airtime sales, bill collection, and bulk payouts—channeling roughly $265 million (or one-fifth of Airtel Money’s total FY26 revenue) straight into its coffers.
- Today (The LSE Listing): Marking a historic milestone for African fintech capital-raising, Airtel Money officially rings the bell on the London Stock Exchange, pricing its multi-billion-dollar valuation against a backdrop of unique regional economic realities.
Supporting Data & Financial Mechanics: The "Digital Envelope" Economy
The financial engine driving Airtel Money’s $7 billion valuation operates quite differently from digital payment ecosystems in Western or mature Asian economies like India.
While platforms like India’s Unified Payments Interface (UPI) facilitate direct, peer-to-peer, account-to-account digital transfers that remain within the digital ledger for commerce, the African mobile-money ecosystem functions primarily as a transit mechanism for physical cash.

An African fintech founder interviewed by The Ken at the India Mobile Congress vividly illustrated this dynamic:
"I put Rs 100 into my Airtel Money wallet, then immediately go to an Airtel Money agent’s shop, show my phone, and withdraw Rs 100 in physical cash, which I then use to buy food, pay rent, or pay a shopkeeper. If I need to send money to someone else, I put cash back into Airtel Money, send it, and the recipient withdraws it again."
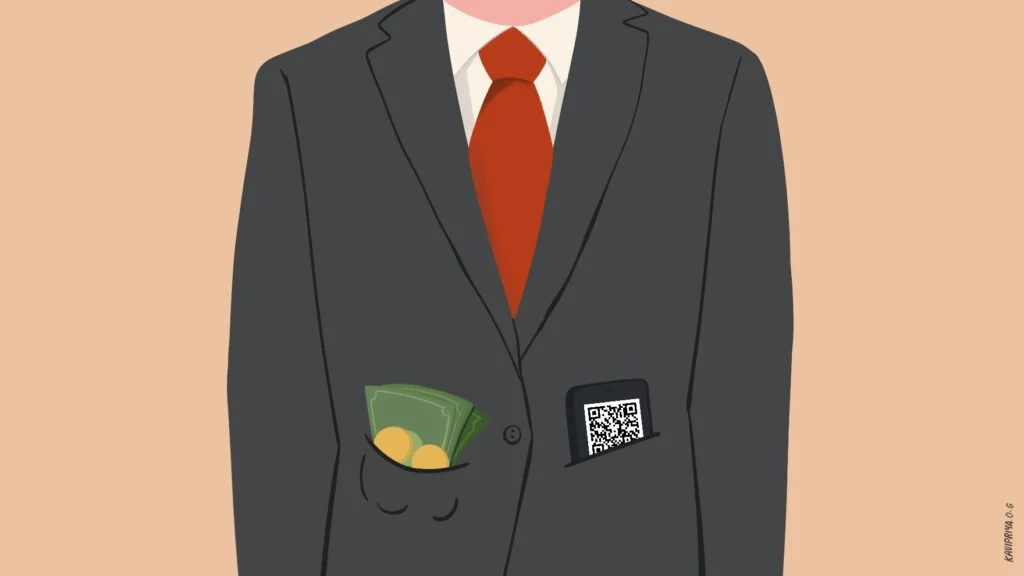
In essence, the mobile wallet acts as a digital envelope designed to move physical cash across geographic distances securely. Supporting this observation, a June study by Affinity Africa regarding the continent’s cash dependency revealed that over 90% of mobile-money value is withdrawn as physical cash the exact moment it hits a user’s account.
Despite its immense scale, Airtel Money is not even the market leader in this category. Its roughly 53 million monthly active users trail behind regional heavyweights:
- Vodacom (M-Pesa): ~103 million users.
- MTN Momo: ~70.8 million users.
Yet, Airtel Money’s integration with its parent telecommunications company provides a structural moat. Because wallet creation is gated behind Airtel mobile subscriptions, user acquisition costs remain remarkably low. Furthermore, internal corporate synergies guarantee a baseline revenue stream: last fiscal year, various entities under Airtel Africa paid Airtel Money $265 million for essential services like airtime distribution and utility bill processing.
Official Responses & Industry Perspectives
The dual nature of Airtel Money—boasting hyper-efficient corporate financials while relying on millions of informal cash agents—has drawn sharp commentary from financial analysts, market strategists, and telecommunications executives alike.
Market analysts reviewing the LSE prospectus have emphasized that the company’s lean staffing model is not merely a cost-saving measure, but an architectural necessity for operating across diverse, fragmented regulatory jurisdictions. By keeping core corporate teams lean in hubs like Kampala, Lusaka, and Nairobi, Airtel Money minimizes bureaucratic friction while maintaining regulatory compliance country-by-country.
Fintech observers note that while Western investors often obsess over metrics like "total digital transaction volume," African fintech valuations must be evaluated through the lens of infrastructure enablement.

"Airtel Money is valued at $7 billion not because Africa has successfully phased out cash," noted one emerging market fintech strategist, "but precisely because Africa never built a nationwide legacy banking network or an instant digital rails system like India’s UPI. Airtel Money became the plumbing for a cash-based economy."
Parent representatives from Airtel Africa have consistently maintained that the public listing of its mobile money division unlocks true value for shareholders by isolating the hyper-growth fintech vertical from traditional telecom capital expenditure cycles.
Implications: What the $7 Billion LSE Listing Means for African Fintech
Airtel Money’s successful debut on the London Stock Exchange carries profound implications for the broader African technology and financial ecosystems.
1. Re-evaluating Fintech Efficiency Metrics
For years, tech valuations have been tied to employee headcounts, engineering bloat, and aggressive scaling of white-collar talent. Airtel Money turns this paradigm on its head. By generating $1.35 billion with roughly 300 employees, it proves that ultra-lean corporate structures combined with massive, decentralized grassroots partnerships can yield world-class operating margins.
2. The Persistence of Cash-Plus-Digital Models
The reality that over 90% of mobile money is immediately withdrawn as cash debunks the myth that developing markets will instantly leapfrog from cash straight to frictionless digital commerce. Instead, a hybrid model has emerged: digital rails are used for transporting value across distances, while physical cash remains king at the point of sale. Fintechs operating in Africa must continue to invest heavily in agent liquidity management rather than software-only solutions.
3. The Telco Advantage in Financial Services
Standalone fintech startups often struggle with high customer acquisition costs (CAC) and regulatory hurdles. Airtel Money’s journey underscores the unbeatable advantage of telco-backed financial services. By piggybacking on an existing cellular subscriber base and leveraging internal B2B enterprise transactions with its parent company, Airtel Money secured a captive market before writing a single line of consumer-facing fintech code.
4. Global Capital Access for African Assets
By listing on the London Stock Exchange, Airtel Money joins an elite group of African-focused enterprises tapping into deep international liquidity pools. This successful debut could pave the way for other telecom spin-offs across the continent—such as MTN’s fintech division—to aggressively pursue international public markets, validating African tech innovation on the global stage.
As trading gets underway in London, Airtel Money stands as a monument to pragmatic financial engineering: a multi-billion-dollar enterprise built on the simple, powerful reality of moving cash through digital envelopes across a continent hungry for financial inclusion.