Main Facts
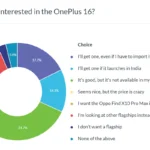
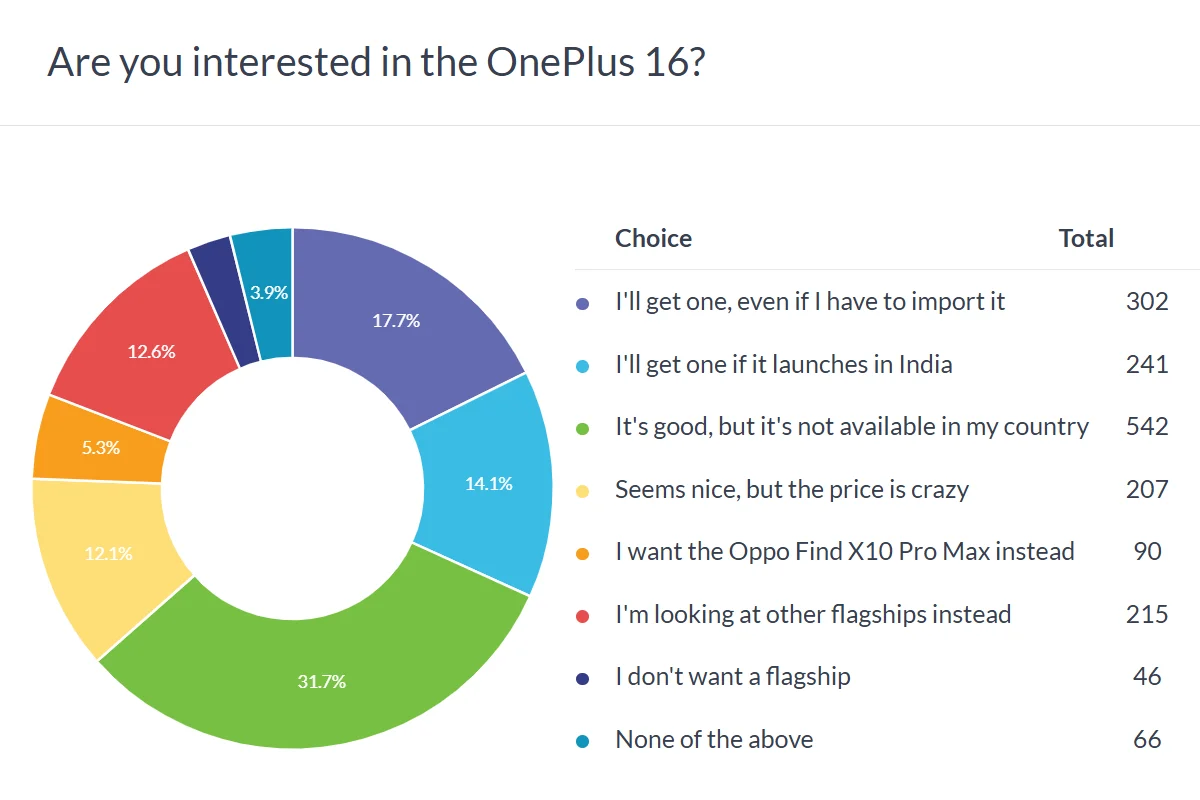
The consumer consensus is officially in, and the results of last week’s highly anticipated community poll paint a fascinating picture of the modern smartphone landscape. According to the data, the OnePlus 16 possesses all the requisite ingredients to be a runaway, globally acclaimed flagship device. There is just one catch: most of the world cannot actually buy it.
Following OnePlus’s strategic retreat from several major international markets, the OnePlus 16 has been designated for a heavily restricted release schedule, officially touching down in only two primary territories: China and India. Despite this severe geographic limitation, the brand’s enduring equity remains strikingly high. Even when evaluated against a backdrop of escalating component costs and a noticeably higher baseline retail price compared to previous generations, the device’s fundamental value proposition continues to resonate deeply with tech enthusiasts around the globe.
The sentiment revealed in the poll data suggests that OnePlus has engineered a hardware package compelling enough to transcend standard logistical barriers. A significant percentage of respondents indicated a willingness to go to extraordinary lengths—including navigating the often complex, expensive, and warranty-compromising world of gray-market importing—just to get their hands on the device. Meanwhile, consumers in India find themselves in an enviable position as one of the sole international beneficiaries of the official rollout, matching the enthusiasm of the domestic Chinese market.
However, the overarching narrative of the poll is one of frustration. The single largest demographic of voters—accounting for nearly a third of total participation—comprises individuals who openly admire the OnePlus 16 and recognize its technical superiority, yet refuse to deal with the operational friction of importing an overseas unit. In an era where rival brands like Oppo are aggressively pushing alternative flagships like the Oppo Find X10 series onto the global stage, the OnePlus 16 still manages to capture the imagination of tech consumers, proving that its allure is built on genuine product merit rather than mere marketing hype.
Chronology
To understand how the OnePlus 16 reached this paradoxical juncture of high demand and low availability, it is necessary to examine the chronological evolution of OnePlus’s corporate strategy and product pipeline over recent years.
Phase 1: The Global Expansion and Peak Integration (2020–2022)
For several years, OnePlus operated under a distinct indie-spirited ethos before fully integrating operationally and structurally with its parent company, Oppo. During this period, the brand expanded rapidly across North America, Europe, and Asia. Devices like the OnePlus 8, 9, and 10 series cemented the company’s reputation as a "flagship killer" that eventually matured into a mainstream luxury contender.
Phase 2: Strategic Consolidation and Regional Retrenchment (2023–2024)
As economic headwinds battered the global smartphone industry, rising supply chain costs, fierce competition from Apple and Samsung, and internal corporate restructuring forced major Chinese original equipment manufacturers (OEMs) to reassess their global footprints. OnePlus quietly began scaling back its direct retail presence in several European and secondary international markets. Rather than competing aggressively for thin margins in saturated Western markets, the company elected to consolidate its efforts where its brand loyalty was ironclad—primarily mainland China and India, while leaving sporadic, highly selective footprints elsewhere.
Phase 3: The OnePlus 15 Benchmark (Late 2024)
Entering the previous product cycle, the OnePlus 15 established a baseline for what consumers expected from the brand: elite performance paired with aggressive, accessible pricing. The maxed-out, top-tier configuration featuring 16GB of RAM and a massive 1TB of onboard storage retailed in China for CNY 5,400. It was widely praised as a benchmark for high-end value.
Phase 4: The OnePlus 16 Announcement and Price Hike (Late 2025/Early 2026)
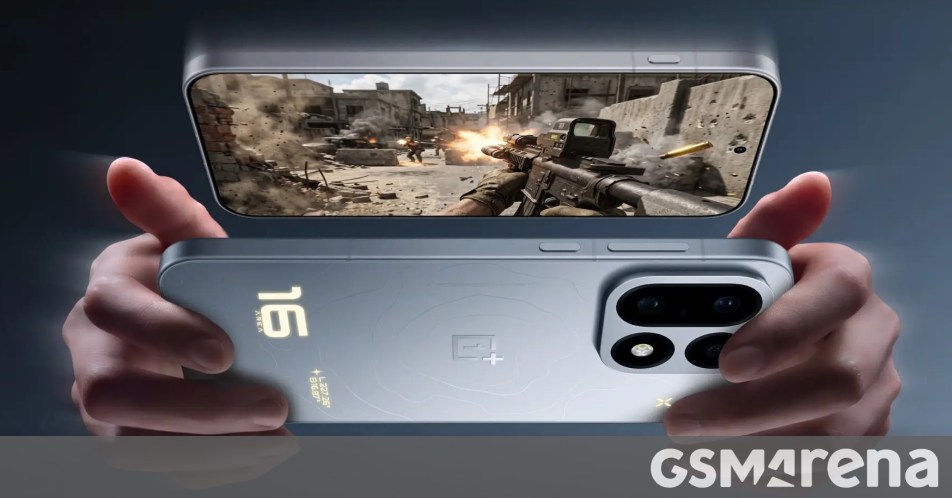
When the OnePlus 16 was formally unveiled, it immediately turned heads—not just for its cutting-edge specifications, but for its steep pricing structure. Driven by soaring semiconductor and memory costs, even the entry-level configuration (featuring 12GB of RAM and 256GB of storage) debuted at a notably higher price point in China, landing at CNY 6,000. This meant the baseline OnePlus 16 cost significantly more than the fully loaded OnePlus 15 from the year prior.
Phase 5: The Poll and Global Backlash (Present Day)
Following the regional launch announcements, industry observers and enthusiast communities launched extensive sentiment trackers, culminating in last week’s poll. The results confirmed that while users were initially startled by the pricing shift, the hardware’s sheer capability neutralized most cost complaints, leaving regional availability as the primary pain point for international fans.
Supporting Data and Market Analysis
A deeper dive into the poll metrics and current market trends reveals critical insights regarding consumer psychology, pricing tolerance, and the shifting dynamics of BBK Electronics’ brand portfolio.
Price Tolerance vs. Market Reality
One of the most surprising takeaways from the poll data is how consumers reacted to the OnePlus 16’s price escalation. In an economic climate where inflation and advanced silicon nodes (such as cutting-edge 3nm processors) have pushed smartphone manufacturing costs to historic highs, price backlash is almost guaranteed.
Yet, only about 12% of surveyed voters categorized the OnePlus 16’s pricing as "crazy" or unjustifiable. This figure is statistically comparable to the baseline percentage of consumers who routinely dismiss all major flagship devices in favor of budget or mid-range alternatives.
To contextualize the financial leap:
- OnePlus 15 (Max Tier – 16GB/1TB): CNY 5,400
- OnePlus 16 (Base Tier – 12GB/256GB): CNY 6,000
Despite the base model of the newer generation commanding a roughly 11% premium over the maximum configuration of its predecessor—while offering less storage and memory out of the gate—consumers largely accepted the adjustment. This indicates that the OnePlus user base views the brand’s engineering and software experience as premium enough to justify flagship-tier pricing, separating OnePlus from pure budget-seeking demographics.
The Import Phenomenon and Regional Disparities
The demographic breakdown of the poll highlights a fractured global audience:
- The Importers: A vocal and technically adept minority of voters are actively pursuing gray-market channels, purchasing Chinese-variant units, and flashing regional ROMs to secure the OnePlus 16.
- The Indian Market Strength: India continues to serve as OnePlus’s most critical international anchor. The enthusiasm registered by Indian respondents mirrors domestic Chinese engagement, proving that brand equity in South Asia remains remarkably resilient despite historical software controversies in prior years.
- The Lost Majority: The largest cohort—accounting for roughly 32% to 35% of respondents—consists of potential buyers who desperately want the device but refuse to navigate the hurdles of importing. These are lost sales directly attributable to corporate geography rather than product deficiency.
Official Responses and Corporate Strategy
The leadership at OnePlus and its corporate parent, Oppo, have remained relatively tight-lipped regarding a reversal of their geographic strategies, but industry analysts have pieced together the underlying rationale.
Historically, operating a localized direct-to-consumer and carrier-partnered retail business in regions like North America and Western Europe requires massive capital expenditures in marketing, regulatory compliance, after-sales service infrastructure, and legal patent maintenance. For a consolidated entity like BBK Electronics, streamlining operations meant cutting redundancies.
By pulling back, OnePlus effectively passed the Western consumer baton to its sister companies:
- Oppo: Positioned clearly as the higher-end, more expensive, design-forward flagship contender, competing directly with global heavyweights through globally distributed flagships like the Oppo Find X10 series.
- Realme: Tasked with capturing the youth-oriented and value-driven segments, though its recent absence of a heavy-hitting GT-series flagship in certain markets has created a notable vacuum.
In corporate statements regarding regional rollouts, executives have consistently emphasized a focus on "sustainable market health" and "tier-one priority regions." While corporate PR departments frame this as targeted optimization, third-party industry observers recognize it as a defensive maneuver designed to protect profit margins in an era of declining global hardware upgrade cycles. Consequently, official statements offer little hope to European and American fans hoping for a sudden return of a localized OnePlus flagship store infrastructure.
Implications
The trajectory of the OnePlus 16 and its reception carry profound implications for both the brand itself and the broader smartphone industry.
1. The Death of the Accessible "Flagship Killer"
The OnePlus 16 confirms a transition that has been unfolding for years: OnePlus is no longer an insurgent brand disrupting legacy giants with artificially low-cost, high-spec novelties. It is a legacy giant. The pricing structure—crossing the CNY 6,000 threshold for base models—places the brand squarely in the traditional ultra-premium category. Consumers have shown they are willing to pay for this pedigree, but it permanently alters the identity that originally built the brand’s cult following.
2. The Opportunity Cost of Geographic Isolation
By restricting the OnePlus 16 to China and India, BBK Electronics is deliberately leaving money on the table. The poll data conclusively proves that demand exists in Western markets. However, corporate calculus dictates that the operational cost of servicing those markets outweighs the revenue generated. This risk-averse strategy protects the bottom line but caps total volume growth, effectively ceding uncontested market share in Western territories to Apple, Samsung, and Google.
3. Fallout for Sister Brands
With OnePlus absent from many Western markets and Realme experiencing an uncharacteristically quiet cycle for high-end GT flagships, Oppo bears the full responsibility of representing the BBK ecosystem in the global arena. While devices like the Oppo Find X10 series are exceptional pieces of engineering, they occupy a different psychological and pricing tier than what legacy OnePlus fans originally loved. The vacuum left by OnePlus creates an opening for other aggressive competitors—particularly emerging foldable and niche slab-phone brands from Asia—to court alienated Western enthusiasts.
Ultimately, the OnePlus 16 stands as a bittersweet monument to modern mobile engineering: a brilliant smartphone that proves its creators haven’t lost their touch, wrapped in a distribution strategy that ensures most of the world can only look on from afar.