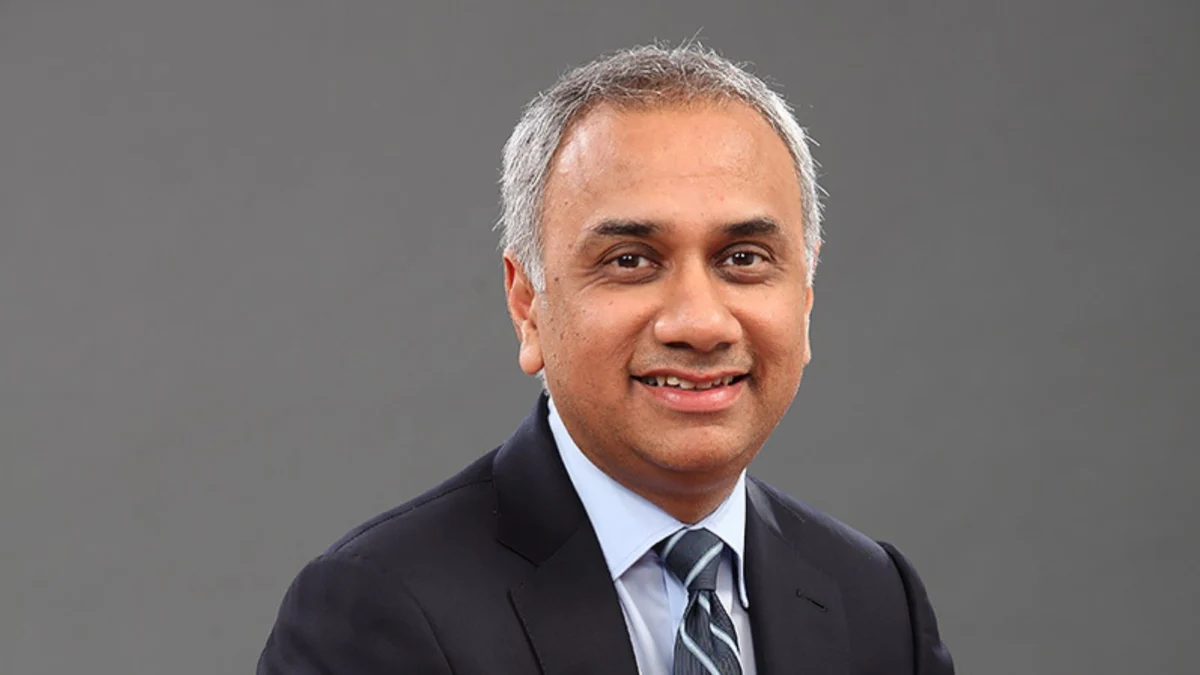
GLOBAL — Amid lingering market skepticism concerning the sustainability of artificial intelligence spending, top technology and investment executives have offered a unified, highly bullish outlook. Speaking at the prestigious Bloomberg New Economy Forum, Infosys Managing Director and CEO Salil Parekh, alongside other global tech and infrastructure leaders, emphasized that global enterprise demand for AI is not only robust but expanding at an unprecedented rate.
Far from being a temporary bubble driven by speculative hype, the panelists argued that the artificial intelligence revolution is transitioning from experimental phases into tangible corporate profitability. However, this exponential growth curve has laid bare critical structural challenges, notably severe bottlenecks in energy supply, data center capacity, and a fragmented geopolitical supply chain that is fundamentally reshaping how nations and multinational corporations approach digital infrastructure.
Main Facts: The Current State of Enterprise AI Demand
The core takeaway from the high-profile panel discussion is that enterprise demand for generative AI, autonomous agents, and technological transformation has moved well beyond the conceptual stage.
- Explosive Revenue Growth: According to Infosys CEO Salil Parekh, AI-driven services—encompassing autonomous agent creation, code generation, legacy technology transformation, and change management—now account for 8 percent of the IT giant’s total revenue. Crucially, this segment is expanding at a staggering double-digit pace quarter-on-quarter.
- The Scale of Opportunity: Industry leaders stressed that the global market has barely scratched the surface of its potential. While current token consumption is heavily concentrated among research institutions and a fraction of the world’s 30 million software developers, the addressable market encompasses more than one billion knowledge workers globally.
- Profitability Realized: Addressing widespread market theories that AI investments are unsustainable money pits plagued by high chip costs and negligible returns, executives affirmed that profitability is rapidly coming into view as enterprises integrate AI directly into their profit and loss (P&L) statements.
- Infrastructure Bottlenecks: The primary constraint on AI expansion is no longer merely a shortage of advanced microchips. Instead, physical infrastructure—specifically data center capacity and reliable energy generation—has emerged as the ultimate limiting factor.
Chronology: From Experimental Chatbots to Enterprise Transformation
To understand the current maturity of the AI sector, it is necessary to trace how the technology has evolved within enterprise boardrooms over the past several years:
1. The Exploratory Phase (2022–2023)
Following the public debut of advanced generative AI models, enterprises rushed to experiment with standalone chatbots and proof-of-concept projects. During this initial phase, AI was largely viewed as an innovative novelty. Critics frequently joked that "AI is everywhere except in the P&L," as companies struggled to tie heavy cloud and token expenditures directly to measurable financial returns. Chip shortages dominated headlines, and market analysts frequently questioned whether the immense capital expenditure required to train large language models would ever yield commercial viability.
2. The Operational Pivot (2024)
By early to mid-2024, corporate strategies shifted from isolated experimentation to core operational integration. IT service providers began deploying sophisticated AI frameworks designed to streamline complex business workflows. Infosys, among other global system integrators, began embedding AI-driven software engineering and automated change management directly into client digital transformation roadmaps.
3. The Current Era: Scaling Autonomous Agents and Infrastructure (Late 2024–Present)
As highlighted at the Bloomberg New Economy Forum, the industry has officially entered a phase characterized by the deployment of multi-step autonomous AI agents and deep enterprise integration. Revenue generation from AI services has crossed the threshold from negligible to a double-digit growth trajectory. Simultaneously, the focus has pivoted away from software algorithms toward the physical world, sparking a massive race to secure power generation, build next-generation data centers, and navigate complex geopolitical restrictions surrounding semiconductor supply chains.
Supporting Data and Expert Perspectives
The panel discussion—which featured Salil Parekh alongside Tillman Global Holdings CEO Sanjiv Ahuja, NTT Data CEO Abhijit Dubey, and Brookfield Asset Management CEO Connor Teskey—provided critical data points and economic insights illustrating the sheer magnitude of the AI boom.
Overwhelming Market Imbalance
Connor Teskey of Brookfield Asset Management pushed back hard against the narrative that AI demand is fragile or cyclical.
"The demand so overwhelms supply at this point that there is going to be a supply-demand imbalance through the end of this decade and probably far beyond that," Teskey stated. He added that the market is witnessing a two-tier opportunity: immediate, highly quantifiable value delivery today, paired with an even larger, unrealized horizon of long-term value creation.
Tapping the Knowledge Worker Economy
NTT Data CEO Abhijit Dubey offered a perspective on market penetration, noting that current compute consumption represents a microscopic fraction of global economic potential.
"We’re still in very early stages, but I think the recipe is starting to become a little bit clearer in terms of how you truly see it in your P&L," Dubey remarked, signaling that businesses are finally cracking the code on monetization.
The Energy and Power Crisis
The conversation quickly pivoted to the physical constraints threatening to cap AI’s explosive trajectory. While chip availability remains tight, power availability is the definitive bottleneck.
Dubey highlighted a glaring disparity in electrical grid stability across major global economies:
- United States: Grid capacity has remained virtually flat for the past three decades.
- China: Grid capacity has doubled every decade for the past thirty years.
Because traditional public utility grids cannot keep pace with the hyper-scale power demands of modern AI data centers, alternative energy solutions have taken center stage. Brookfield forecasts that by 2030, at least one-third of all electricity capacity dedicated to tech infrastructure will rely on off-the-grid, onsite generation sources—including renewables, advanced battery cells, and nuclear energy.
Official Responses and Strategic Adaptations
Major global technology firms and asset managers are rapidly restructuring their operations to capture this unprecedented wave of demand while mitigating infrastructural and geopolitical risks.
- Infosys’s Strategic Focus: Salil Parekh emphasized that Infosys is actively capitalizing on enterprise needs by moving beyond basic IT outsourcing. By helping clients build autonomous AI agents, restructure legacy codebases, and manage large-scale digital transformations, Infosys has turned AI into a high-growth revenue engine. The firm’s ability to scale these services while maintaining margin discipline has positioned it as a key beneficiary of corporate tech spending.
- Brookfield’s Infrastructure Pivot: As an asset management giant, Brookfield is aggressively investing in the physical underpinnings of the digital economy. Recognizing that power is the ultimate constraint, the firm is heavily backing green energy, battery storage, and nuclear power projects designed to supply dedicated, off-grid electricity directly to data center operators.
- Tillman Global’s Geopolitical Navigations: Sanjiv Ahuja pointed out that the global technological supply chain is undergoing its most dramatic fragmentation in over half a century. With data treated as a prized national commodity, companies are forced to navigate fractured ecosystems where specific semiconductors and hardware components are legally restricted to certain geographic regions or hyperscalers.
Implications: Strategic, Economic, and Geopolitical Ramifications
The convergence of massive AI demand, infrastructure bottlenecks, and geopolitical fragmentation carries profound implications for the global economy over the remainder of the decade.
1. Corporate Profitability and Valuation Shifts
The validation offered by tech CEOs that AI is finally delivering measurable P&L results is likely to alleviate investor anxieties regarding an "AI bubble." As enterprises prove that automated agents and AI-driven efficiencies directly reduce operational costs and accelerate time-to-market, capital is expected to continue flowing aggressively into enterprise software and IT transformation partners like Infosys.
2. The Energy Transition Acceleration
The artificial intelligence boom has inadvertently become one of the single largest catalysts for the global energy transition. Because traditional power grids are incapable of absorbing the load required by massive server farms, tech companies and asset managers are being forced into direct partnerships with the energy sector. The race to secure baseload power will permanently intertwine the fortunes of Big Tech with the nuclear, solar, wind, and battery storage industries.
3. Geopolitical Fragmentation and Digital Sovereignty
National security considerations are fundamentally altering the geography of technology infrastructure. As Sanjiv Ahuja noted, data is now regarded as the world’s fastest-growing commodity and an asset of vital strategic importance. Governments across the globe are no longer willing to rely on centralized, cross-border digital infrastructure. Consequently, regional fragmentation will accelerate, with individual nations demanding localized AI data centers, sovereign cloud environments, and domestic semiconductor supply chains.
Conclusion
As articulated by the global leaders at the Bloomberg New Economy Forum, artificial intelligence has successfully graduated from a speculative technological experiment into an indispensable engine of global commerce. While severe challenges remain—ranging from the daunting task of powering massive data centers to navigating a fractured geopolitical landscape—the overarching trajectory is clear: enterprise demand is insatiable, profitability is materializing, and the structural transformation of the global economy is moving forward at an accelerating pace.