New Delhi: In a landmark move designed to radically overhaul business sentiment and foster a trust-based tax architecture, the Goods and Services Tax (GST) Council approved a sweeping package of structural and procedural reforms. Announced following the conclusion of its 57th meeting, the decisions mark a decisive shift away from stringent punitive measures toward a progressive, compliance-friendly taxation framework.
Union Finance Minister Nirmala Sitharaman, addressing a press conference after the meeting—the first gathering of the Council in 13 months—emphasized that the overarching philosophy of the government is rooted in trust. She stated that tax processes must be designed to trust businesses rather than function as overly intrusive mechanisms.
The reform package addresses long-standing grievances from India Inc. regarding regulatory overreach, providing structural relief on arrests, show-cause notices, vehicle inspections, penalties, and liquidity management. Barring a few exceptions slated for earlier implementation, most of these sweeping recommendations will officially come into force on April 1, 2027.
1. Main Facts: Core Reforms at a Glance
The 57th GST Council meeting delivered critical changes across multiple operational frontiers of India’s indirect tax regime:
- Removal of Pre-Prosecution Arrest Powers: Tax officers can no longer execute arrests at the pre-prosecution stage based on mere anticipation or suspicion of criminality.
- Hike in Prosecution Threshold: The financial threshold triggering criminal prosecution has been elevated fivefold, moving from Rs 1 crore to Rs 5 crore.
- Rationalization of Show-Cause Notices: A retroactive minimum threshold of Rs 10,000 has been established for the issuance of show-cause notices.
- Streamlined Vehicle Interception: Vehicles carrying goods can now only be intercepted by tax officers belonging to either the supplier’s or the recipient’s home state, and strictly on the basis of “specific intelligence” backed by due authorization.
- Faceless Tax Assessments: The Centre announced a parallel initiative to introduce faceless tax assessments for Central GST (CGST) taxpayers registered across multiple states.
- Penalty Reductions: Maximum general penalties are slashed from Rs 25,000 to Rs 10,000. For non-fraud cases, a lower penalty of 5% applies, and the mandatory minimum penalty condition of Rs 10,000 has been scrapped.
- Accelerated Automated Refunds: Ninety percent of eligible refund claims will now be processed and sanctioned automatically via system-based workflows within three working days of acknowledgment, down from the previous seven-day timeline.
- Widening Refund Ambit: Input tax credit (ITC) refunds are now extended to cover input services under inverted duty structures as well as capital goods.
2. Chronology: The Path to the 57th GST Council Meeting
To fully comprehend the gravity of Thursday’s announcements, it is vital to trace the sequence of policy events leading up to this structural juncture:
- September 2025: The GST Council executed sweeping cuts in indirect tax rates on various goods and services, a major rationalization drive that successfully stabilized core consumer and industrial pricing structures.
- October 2025 – September 2026 (The 13-Month Interregnum): Following the major rate cuts, the Council maintained a prolonged hiatus from major structural announcements, allowing administrative bodies to absorb the economic impact of the rate rationalization. During this period, industry bodies consistently lobbied against aggressive enforcement, overzealous tax audits, and rigid pre-prosecution measures.
- October 2026 (The 57th Meeting): Meeting after a gap of 13 months, the GST Council reviewed its comprehensive agenda. It approved nearly all items presented before it, save for two specific input tax credit issues referred to a Committee of Officers for a three-month review.
- November 1, 2026: The implementation date for expanding refund rules to include input services under the inverted duty structure.
- April 1, 2027: The formal enforcement date for the vast majority of the Council’s sweeping structural recommendations, including the removal of pre-prosecution arrest powers, revised vehicle interception guidelines, and capital goods ITC refund frameworks.
3. Supporting Data and Regulatory Mechanics
The economic mechanisms behind the 57th GST Council reforms are structured to inject vital liquidity into the corporate ecosystem while curbing administrative harassment.
Decriminalization and Threshold Revisions
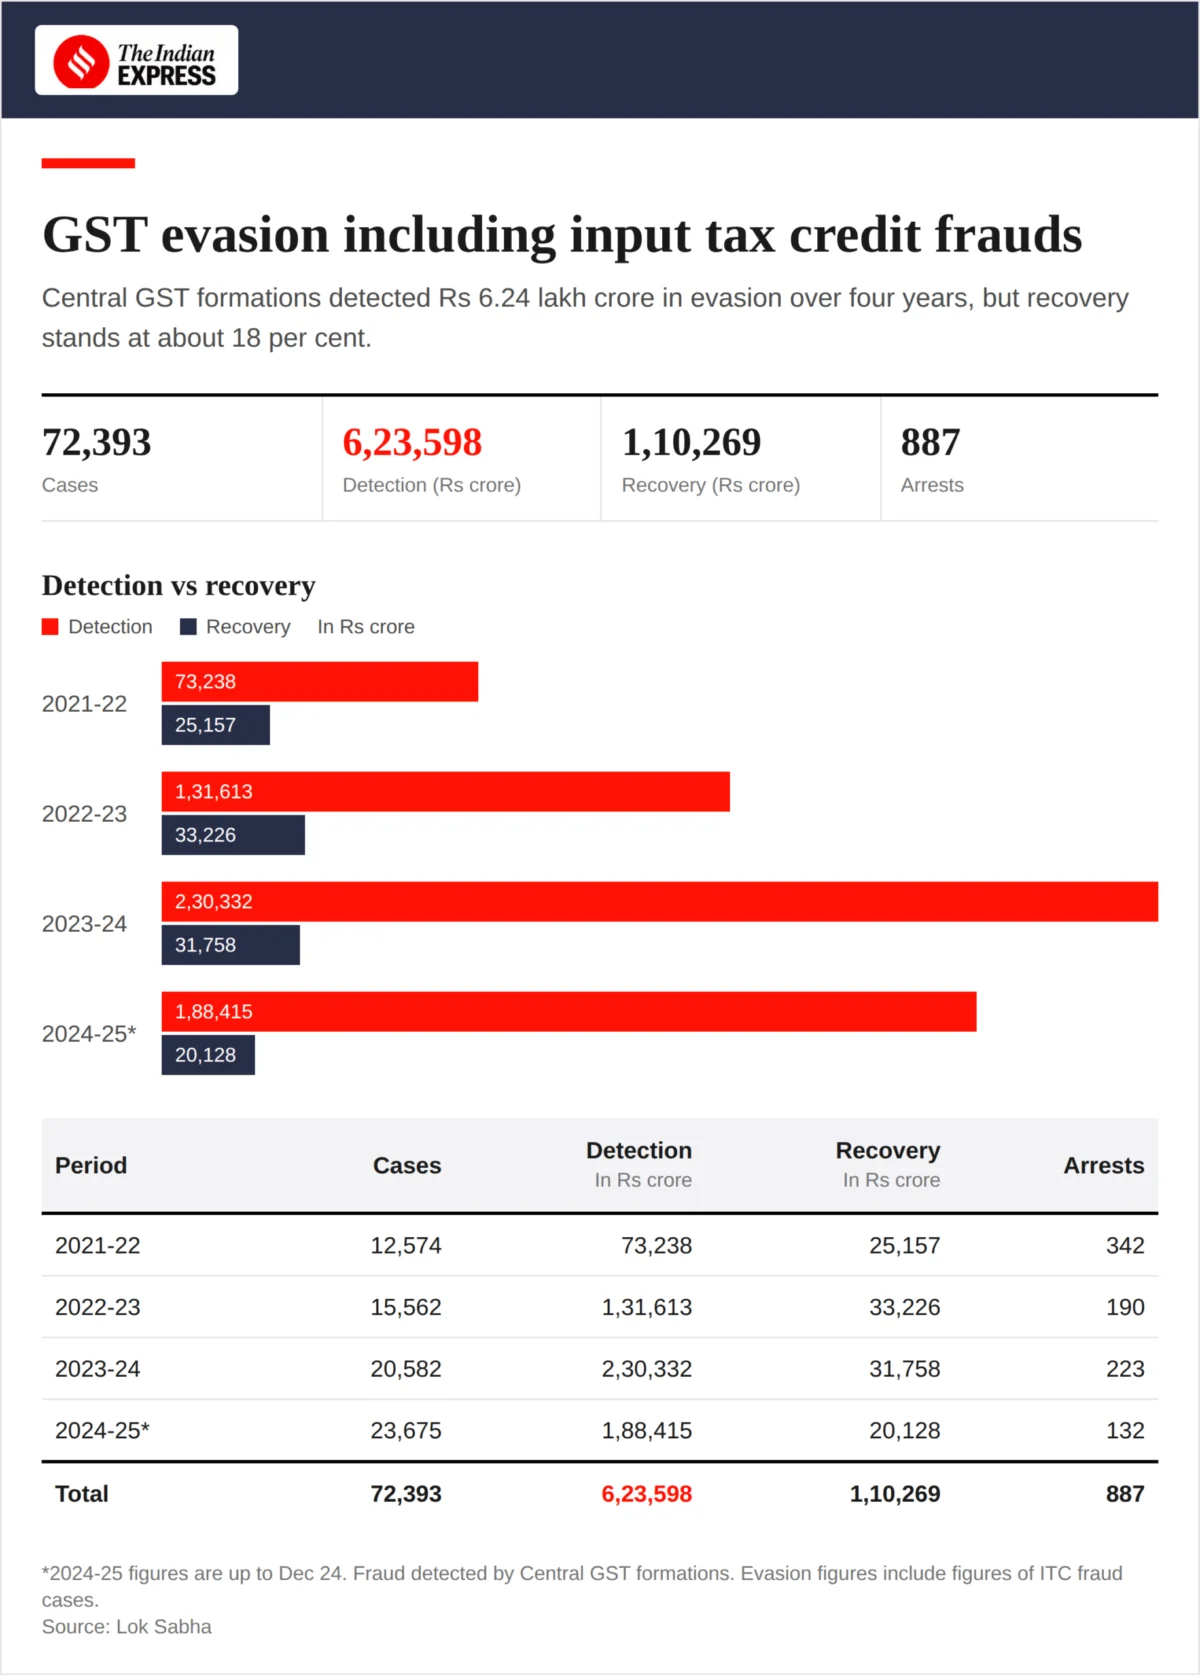
Under the legacy framework, tax authorities wielded broad discretionary powers to detain individuals and initiate prosecution at relatively low thresholds of alleged evasion (Rs 1 crore). By quintupling this threshold to Rs 5 crore and stripping tax officers of pre-prosecution arrest powers, the Council has aligned administrative deterrence with international best practices.
Finance Minister Sitharaman clarified the legal nuance:
“This law itself provides for prosecuting people who have committed a criminal thing if you build a prima facie case. But, the tax officer in anticipation of something, and thinking that he has got a case before him, which has got a criminality, cannot (make the) arrest. Build your prosecution up, then our own law gives the provision for prosecuting. Take them to prosecution at that time.”
Working Capital Liberation via Automated Refunds
Liquidity constraints have historically plagued fast-moving consumer goods (FMCG) and manufacturing firms operating under inverted duty structures (where tax on inputs exceeds tax on final outputs).
- Automated Processing: 90% of claims will be automatically cleared in 3 working days.
- Capital Goods ITC: Refunds on input tax credit for capital goods will be phased out and spread uniformly over 60 months.
- Late Filers and Errors: Taxpayers who experience delays, operational mistakes, or temporary payment lapses will no longer face disproportionate harassment; penalties will be restricted strictly to recovery actions, standard interest, and proportionate penalties.
4. Official Responses and Policy Intent
Reactions from the Union Government underline a profound shift in mindset regarding tax administration. The overarching narrative from the Ministry of Finance is that compliance should be driven by technology and transparency rather than fear and coercion.
Describing the package as a milestone addressing “99% of issues” raised by the corporate sector, Sitharaman maintained that while the immediate reforms are comprehensive, the door for future improvements remains open.
Furthermore, addressing multi-state operational friction, the Centre initiated a move toward faceless tax assessments for CGST registrants. This mechanism will eliminate physical touchpoints between taxpayers and field officers, minimizing localized discretionary friction and ensuring uniform application of tax protocols across jurisdictions.
On the subject of future rate adjustments, the Finance Minister noted that the massive rate rationalization exercise conducted in September 2025 has largely stabilized the indirect tax architecture. Consequently, future adjustments to tax rates are expected to follow an annual review cycle, though urgent anomalies will remain within the purview of the Council if circumstances demand immediate intervention.
5. Implications for Businesses and the Broader Economy
The long-term economic and operational implications of the 57th GST Council decisions are profound across several dimensions:
1. Rejuvenation of Business Sentiment
For years, trade associations and chambers of commerce pointed to aggressive tax enforcement as a primary inhibitor of domestic investment. By removing pre-prosecution arrest powers and scaling back the general penalty structure, the government has directly targeted the "fear factor" in business operations. Companies can now focus on capital allocation and expansion without the constant threat of arbitrary enforcement actions.
2. Elimination of Interstate Harassment on Logistics
The restriction preventing tax officers from stopping transit vehicles unless they belong to the supplier’s or recipient’s state—and exclusively on the basis of verifiable "specific intelligence"—brings predictability to India’s supply chains. It curtails localized transit delays and administrative hurdles that previously hampered frictionless interstate commerce.
3. Relief for Working Capital-Intensive Sectors
FMCG, heavy manufacturing, and infrastructure sectors stand to gain substantially from the expanded refund scope. Allowing input service credits under inverted duty structures and spreading capital goods ITC refunds over 60 months ensures that corporate balance sheets are not starved of essential cash flows.
4. Transition to a Mature Compliance Culture
By pairing higher thresholds for prosecution (Rs 5 crore) and minimum notice values (Rs 10,000) with strict technological safeguards like automated 3-day refunds and faceless assessments, India is signalling a maturation of its tax regime. The framework shifts from policing compliance to enabling it, setting the stage for robust, trust-driven economic growth as the country marches toward the 2027 implementation horizon.