










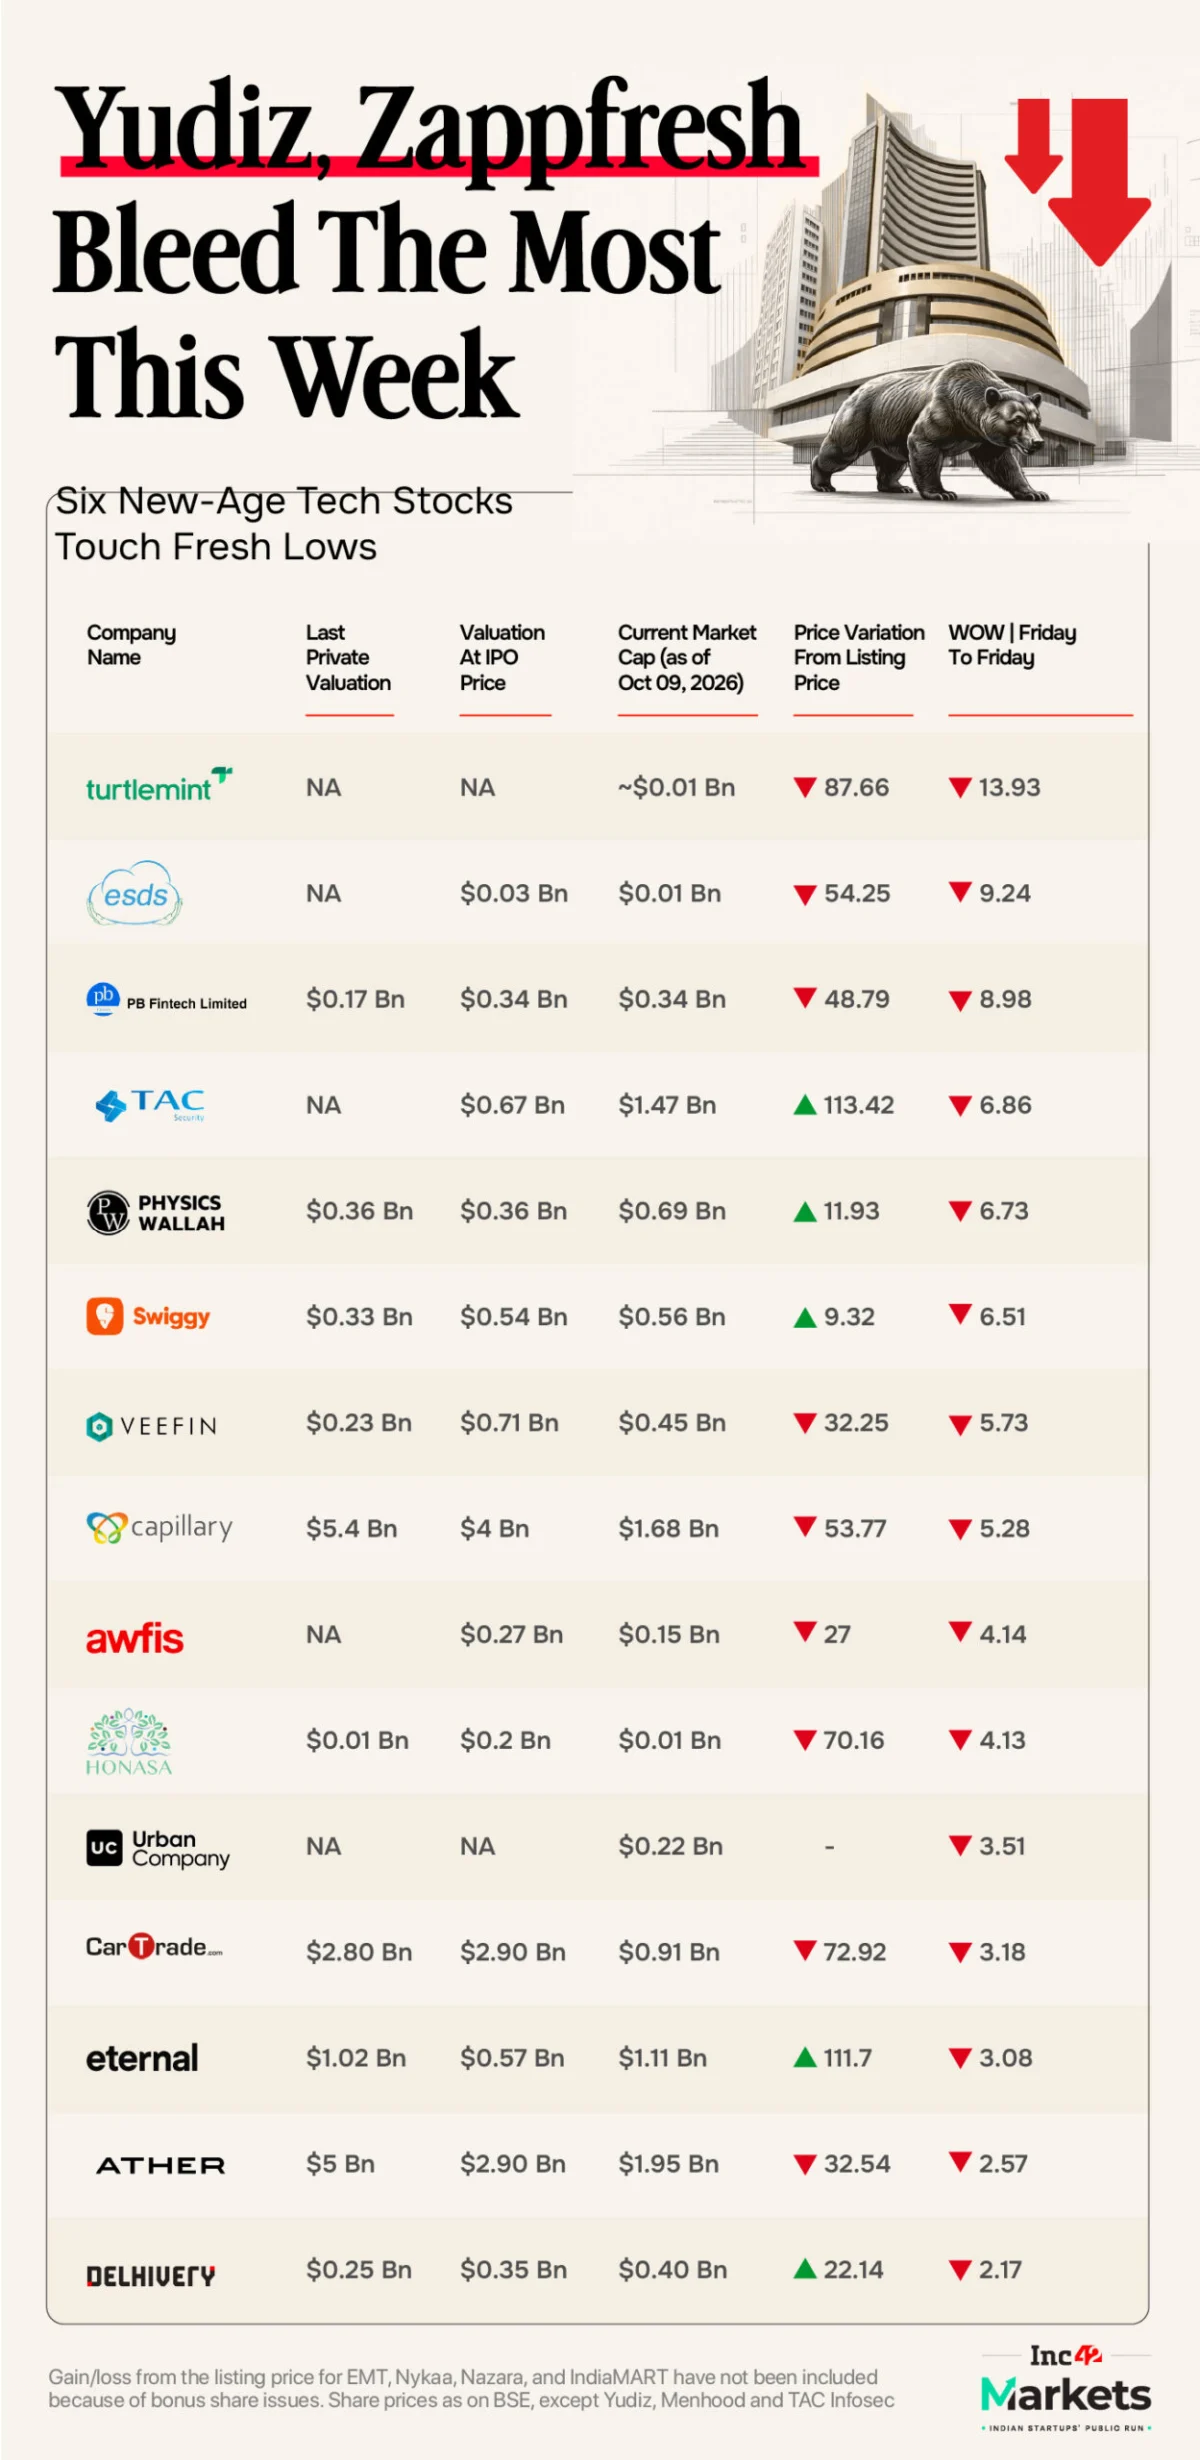
The Indian stock market witnessed a remarkable turnaround this week, as benchmark indices successfully snapped an eight-week losing streak. Despite a midweek bout of volatility characterized by heavy selling, the broader market sentiment improved, providing a much-needed tailwind for the new-age technology sector. Among the 66 tracked tech stocks, the recovery was uneven but encouraging: 36 companies saw gains ranging from a modest 0.1% to a robust 25%, while 30 others faced downward pressure, with declines spanning 0.23% to 13.93%.
Main Facts: The Winners and The Losers
The rally was spearheaded by MobiKwik, which emerged as the top performer of the week, surging nearly 25% to reach ₹245.40. This momentum was supported by other notable gainers, including PhysicsWallah (+19.68%), Fino Payments Bank (+8.9%), Nykaa (+5.97%), and Eternal (+3.14%).
The week also saw several entities hit significant milestones. E2E Networks, Shadowfax, SEDEMAC, Zelio E-Mobility, Aequs, and Kissht all touched fresh highs, reflecting strong investor appetite for specific growth stories. Conversely, the market’s underbelly remained strained; IndiaMART, Fractal, Turtlemint, PB Fintech, Klassroom, and Yudiz hit fresh lows. Yudiz led the decliners, plummeting 13.93% to ₹20.70, followed by the BSE SME-listed Zappfresh, which slid 9.24% to ₹54.90.
A significant addition to the coverage landscape this week was the debut of AceVector (the parent company of Snapdeal). Following its listing on Monday, October 5, the stock closed the week at ₹30.61—an 8.16% premium over its listing price of ₹28.30, yet still trailing its IPO price of ₹32 by 4.3%. With this inclusion, the combined market capitalization of the 67 companies under Inc42’s coverage rose to $154.71 Bn, up from $153.61 Bn the previous week.
Chronological Market Dynamics
The week began with cautious optimism, which was tested mid-week as institutional investors reacted to global geopolitical tensions and shifting domestic monetary policy. The RBI’s decision to hike the repo rate by 25 basis points to 5.50%—coupled with a shift toward "calibrated tightening"—introduced a layer of uncertainty.

By mid-week, reports concerning a potential delay in the UPI Merchant Discount Rate (MDR) framework caused a sharp dip in fintech stocks, including a 4.5% decline in MobiKwik on Thursday. However, the markets showed resilience by the week’s close. Foreign Institutional Investors (FIIs) continued their selling streak for the eighth consecutive week, offloading ₹30,294 Cr worth of equities. Their impact, however, was mitigated by Domestic Institutional Investors (DIIs), who injected ₹30,313 Cr into the market, providing the liquidity necessary to sustain the recovery.
Supporting Data and Sectoral Performance
The technology sector’s performance was deeply intertwined with quarterly business updates and internal strategic moves.
Quarterly Business Updates
- Nykaa & Honasa: Both entities provided positive growth outlooks. Nykaa projected Q2 FY27 net revenue growth in the high-twenties percentage range, while Honasa forecasted net sales value growth in the low-thirties.
- Aye Finance: While its Q2 Assets Under Management (AUM) grew 26% YoY to ₹7,604 Cr, the stock faced downward pressure.
- Fino Payments Bank: Demonstrated aggressive growth with a 223% YoY surge in September loan referral disbursals to ₹278 Cr.
Institutional and Founder Activity
The week was marked by significant capital maneuvers:
- Founder Pledging: ideaForge CEO Ankit Mehta pledged 2.8 Lakh shares worth ₹20.56 Cr for personal requirements. Meanwhile, Ola Electric’s Bhavish Aggarwal pledged a 4.32% stake to participate in the company’s ₹1,000 Cr rights issue, priced at ₹27 per share.
- Stake Sales: Peak XV reduced its holding in Awfis by selling 12.2 Lakh shares for ₹29.8 Cr. Similarly, TPG continued its exit strategy from Shadowfax, offloading 40 Lakh shares for ₹114.8 Cr—the fourth such sale in three months.
Operational Restructuring
Strategic consolidation remained a theme. Meesho announced plans to invest an additional ₹50 Cr in Kirana Club, continuing its long-term strategy in the kirana retail space. Fractal underwent leadership changes, appointing TPG MD Vivek Mohan as Chairman while expanding its footprint by incorporating a subsidiary in the Qatar Free Zones. GlobalBees moved to exit its 51.54% stake in Mush Textile for ₹5.69 Cr, streamlining its portfolio.
Official Responses and Expert Commentary
Market experts view the current climate as a transitional period defined by global headwinds. InvestorAi CEO Bruce Keith noted that the RBI’s recent rate hike was a necessary move to address inflationary pressures, a weak rupee, and the geopolitical impact of oil prices consistently hovering above $100. "The RBI’s stance signals that further hikes are on the horizon, especially as the impact of external climatic factors like El Niño becomes clearer," Keith remarked.

Ajit Mishra of Religare Broking emphasized the technical levels to watch for in the coming week. "Nifty has found support at the 22,200–22,400 range. A sustained move could see it climbing toward 23,000, though we must remain vigilant regarding crude oil prices and global bond yields," Mishra advised.
Implications for the Broader Market
The broader economic environment is shifting. The GST Council’s recommendation to raise the prosecution threshold from ₹1 Cr to ₹5 Cr and withdraw arrest powers represents a significant relief for small and medium-sized enterprises (SMEs), potentially reducing the compliance burden and litigation risk for the listed tech companies operating in that space.
The Case of MobiKwik and RentoMojo
The volatility surrounding MobiKwik highlights the market’s sensitivity to regulatory news. While the prospect of UPI MDR fees offers a potential revenue tailwind, the news of a possible delay to January 2027 serves as a reminder of how policy timelines dictate short-term stock movements. Despite this, the company’s turnaround to a positive EBITDA of ₹15.8 Cr and a 50% YoY rise in GMV suggests a strengthening fundamental base.
RentoMojo’s performance is equally illustrative. Despite a 38.7% YoY decline in profit to ₹7.8 Cr—partly due to an exceptional loss from a warehouse fire—the stock rallied 12.34%. This suggests that investors are looking past short-term bottom-line shocks, focusing instead on the 51.1% revenue growth and the 41% increase in live products.
Looking Ahead: The Road to Stability
As we move into the next week, the market focus will shift toward the release of Consumer Price Index (CPI) and Wholesale Price Index (WPI) data for September. These metrics will be critical in determining whether the RBI’s "calibrated tightening" is yielding the desired control over inflation.

For the new-age tech sector, the coming weeks will likely be defined by how companies manage their operational costs against the backdrop of rising interest rates. The divergence between companies hitting fresh highs and those plumbing new lows underscores a maturing market that is increasingly prioritizing sustainable cash flows over speculative growth. Investors would do well to balance their enthusiasm for high-growth tech narratives with a pragmatic assessment of institutional stake movements and regulatory dependencies.
With the Nifty currently navigating a delicate support zone, the tech sector’s ability to remain resilient in the face of potential global volatility will be the ultimate litmus test for the market’s recovery. As the GST council reforms begin to take hold and quarterly results continue to trickle in, the tech ecosystem remains a high-beta space that demands both agility and a long-term strategic horizon.



